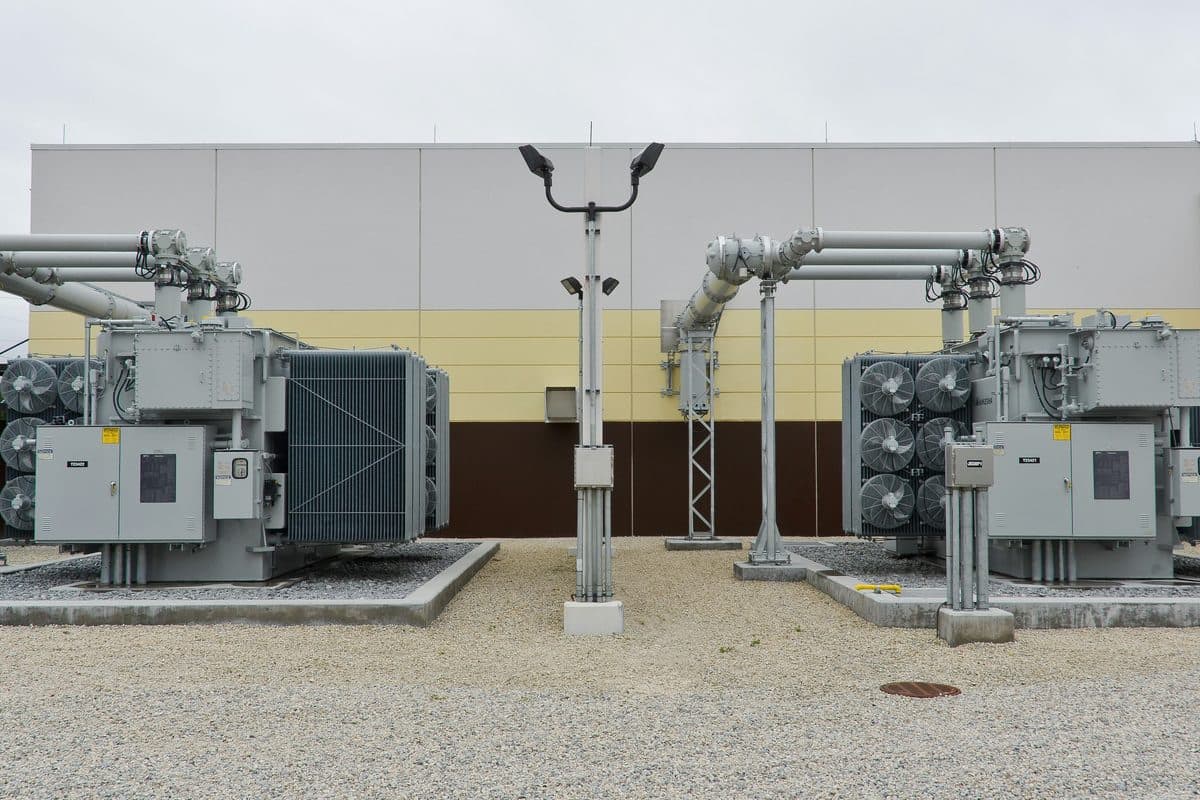
Fuel Cells & On-site PowerFuel cells can buy AI data centers time, if the site is ready.
Fuel Cells & On-site Power/NRG 인사이트
Fuel cells can buy AI data centers time, if the site is ready.
On-site fuel cells can bring power forward, but equipment delivery is only one part of a working plant. Gas service, permits, electrical works and dependable operation decide when a data center can use that power. US industry forecasts show growing interest; Korea has auction and direct-trading routes with different conditions. The useful comparison is the cost and date of equally dependable power at a specific site.
Solid Oxide Fuel Cells
개인정보를 소중히 다룹니다
저희는 사이트 이용 현황을 파악해 서비스를 개선하기 위해 쿠키를 사용합니다. 필수 쿠키는 항상 적용되며, 전체 허용과 전체 거부, 또는 원하시는 항목만 선택하실 수 있습니다. 자세히 보기
For a new AI data center, how soon power can be on site has become a deciding factor, and on-site generation is one way to shorten the wait.
리서치 본문은 영문으로 제공됩니다.
Fuel cells offer a way to start computing before a grid connection is ready. The value lies in the interval a completed on-site plant can actually cover. A module delivered to a prepared site and a new campus reaching commercial operation are different milestones.
NRG reads this market through three conditions: when dependable power is ready, whether the buyer can procure it, and what continuous operation costs. Those conditions can clear at different times. A national takeoff year or a headline order book cannot substitute for a site-level decision.
Interest is growing; installations are a separate measure
Rystad Energy’s June 2026 analysis counts about 9 GW of fuel cells contracted for data centers, including framework agreements. It cites an industry manufacturing metric of 1.8 GW a year, with operational and planned output on track for 4 GW a year by 2030. The book is equivalent to five years at the earlier rate, an NRG calculation. Framework ceilings are not all firm orders, and the ratio is neither a delivery promise nor a measure of how long a shortage lasts.
Commitments and manufacturing are different stages
9 GW / 1.8 GW a year
Rystad Energy’s June 2026 aggregate includes framework ceilings. Dividing by the cited annual manufacturing metric gives five years of equivalent output, not a lead time. Shipment, site commissioning and load served remain separate.
A supplier-sponsored 2026 power survey, fielded in November 2025, covered 152 respondents across industry roles, 84% based in the United States. In the fully-on-site question, hyperscalers and colocation providers (n=92) expected roughly one-third of US sites to run fully on-site by 2030, on average. A separate developer question (n=92) put 73% in the actively evaluating on-site power category. These question-specific expectations and intentions are not measured installations or SOFC market share.
The denominators also matter. Cleanview’s mid-2026 measure concerns announced planned capacity; Enverus forecasts the share of new US load additions served on-site over 2026–2030; Rystad models the share of total US capacity in 2030 likely to pursue dedicated generation. The IEA’s April 2026 estimate puts on-site supply at 6–13% of US data-center load growth under its scope. These are different questions, not a common adoption range.
Compare complete projects on the same clock
The IEA’s April 2026 outlook estimates global data-center electricity use at about 485 TWh in 2025 and projects about 950 TWh in 2030. DOE/LBNL’s 2025 Update, released in June 2026, replaces its earlier US study: the 2030 reference case is 649 TWh, with compounded-uncertainty scenarios of 521–843 TWh. History is updated through 2024; later years are modeled, not current observed consumption.
Rystad’s 2026 analysis gives a three-to-six-year US grid wait for large loads. Enverus’s August 2026 modular-project comparison gives 18–24 months to deployment, fuel cells among the technologies. That includes a project rather than merely a generator arriving. Gas availability, applicable permissions, electrical works and commissioning can move the date. The IEA’s October 2026 policy report adds a check on grid integration; it does not replace April’s demand forecast.
Milestone
What has finished
What remains
Equipment delivery
The ordered module has arrived
Site readiness, installation, testing and permission to operate may remain
Prepared-site installation
A bounded system is installed on a site already made ready
This does not establish the completion time for a new campus
Project commercial operation
Generation and required site tracks are ready to supply the defined load
Reliability, maintenance and ongoing fuel/service obligations continue
Clocks used in this article and the paired report. Source: Rystad Energy; Enverus; NRG analysis.
For turbines, one large maker’s September 2026 book contains 122 GW of orders and reservations, including 58 GW of reservations. Against a cited 20 GW annual manufacturing run rate, that is 6.1 years of equivalent output, an NRG calculation. Reservations, firm orders and shipments have different status; the ratio does not tell a new customer its delivery date.
Factory-built generation can shorten part of a project. Gas service, site works and permits still have to be ready before the data center receives usable power.
The premium is a model, not a profit conclusion
The paired report reproduces a narrow generation-cost example from EIA planning inputs: roughly $135/MWh before a credit, or $103/MWh if an assumed 30% credit is fully realized on the modeled capital basis. It uses a 10 MW planning plant, 90% running and an assumed 8% discount rate over 20 years. Fixed upkeep and $0.72/MWh variable O&M are included. The capex is in constant 2025 dollars; the gas and grid benchmarks are 2026 nominal inputs. It is an illustration, not a site quotation or a fully consistent real-dollar valuation.
The gas input is a $3.48/MMBtu Henry Hub forecast, not firm gas delivered to the site. EIA’s August 2026 industrial average is $4.34 per thousand cubic feet, a different unit and customer basis. The report’s $3–6/MMBtu fuel sensitivity produces about $132–151/MWh before credit. Connection charges, firm transport and local basis must be checked separately.
The model excludes extra stack replacements, degradation, spare generation, gas connection and site power-conditioning costs. IT capacity, facility load and generation nameplate cannot be treated as the same megawatt: cooling and other overhead raise facility demand, while redundancy raises required generation. A tax credit also depends on eligible property, construction timing, statutory restrictions and realization; it is not an automatic reduction on every project cost.
A generation-cost premium can be compared with assumed gross AI-service revenue only after the units and recipients are matched. A colocation owner may not earn that revenue, and gross sales are not margin. The report therefore shows fuel and running sensitivities on a common generation basis. Halving earning utilization would halve assumed revenue and double any premium-to-revenue ratio, all else equal; it does not establish affordability.
Solid oxide cells’ high-temperature, slow-start behavior generally suits sustained operation. That supports a bridge or base-load role, while emergency duty depends on the complete system design. A slowly starting unit alone is not a general substitute for fast-restoring backup; continuously hot or hybrid arrangements need their own engineering review.
DOE’s 2024 class-level durability status, 40,000–80,000 operating hours in 2023, is a benchmark rather than an AI-fleet stack-life distribution. The report preserves an explicitly uninterrupted-running replacement illustration. At 90% running, the same assumed thresholds imply fewer changes before the end of the modeled plant life. Degradation at a benchmark threshold does not itself establish that every system needs a complete stack replacement.
Korea: a route has to fit the buyer and the site
The general-hydrogen auction and direct site procurement are different routes. The official 2025 auction results show 52 awards totaling 1,355 GWh a year; all winning plants were 20 MW or smaller. That is the distribution of those awards, not a universal legal cap on on-site generation.
The official October 30, 2026 opening offers 930 GWh a year in general hydrogen and a separate 500 GWh a year in clean hydrogen. General-market selection is expected in December 2026, with operation by 2029; clean-market selection is expected in June 2027, with operation by 2030. These are annual energy contracts, not factory shipments or capacity already operating.
Contracted energy needs a running assumption
930 GWh a year
At an assumed 85% capacity factor, the general-hydrogen volume corresponds to about 125 MW: 930,000 MWh / (8,760 hours × 0.85), an NRG calculation. This is a conversion, not an awarded capacity total or an eligibility limit.
A direct-trading notice effective June 23, 2026 provides a contract route within designated distributed-energy zones. Region, participants, supply arrangements and applicable rules still have to fit the project. The existence of that route does not establish a commercially workable campus-scale contract for every site. Conversely, an auction’s small winners do not prove that no route exists.
Grid expansion and local procurement rules shape a site’s options. A long transmission project is a different clock from an individual service connection.
NRG’s conclusion is conditional market readiness. Procurement permission, the delivered-power date and lifetime operating economics must meet at the same site. This explains how similar equipment can face different adoption conditions without relying on a particular maker’s production story or predicting a fixed national lag.
Outlook through 2030: watch conversion into usable power
Whole-technology SOFC market forecasts and data-center fuel-cell forecasts cover different populations. MarketsandMarkets’ July 2025 edition projects $2.98bn in 2025 to $11.61bn in 2030. BCC’s February 2026 release projects $9.6bn in 2030 but gives inconsistent base-year figures. Rystad’s $30bn revenue path uses fuel-cell market wording whose public detail does not establish a data-center-only systems denominator. They are attributed model outputs, not comparable measurements.
Path
What must happen
What to observe
Wider deployment
Frameworks become firm purchases, shipments and commissioned dependable power
Operating sites and disclosed field/service performance
Bridge role persists
Grid power becomes usable while on-site fleets remain economic to operate
Actual connection dates and retained operating duty
Deployment disappoints
Fuel, permissions, site works or lifecycle costs interrupt conversion
Delayed commissioning, utilization and maintenance costs
Conditional paths through 2030, not probability forecasts or bounds on installations. Source: NRG analysis of the public record.
Calendar 2026–2030 contains five annual buckets; it is not five forward years from this November revision. The paired report retains a public-input supply illustration over those buckets, clearly separated from actual installations. It assumes output allocation and timing rather than observing them. No independent 2031 numerical forecast is implied.
“The useful unit is dependable power delivered to a defined load, on a usable date and under a contract the buyer can execute.”
— Nathan Research Group, NRG Insights
The market earns its time advantage only when the whole site is ready. Order maturity, fuel firmness, permit applicability and the cost of keeping power available are therefore as useful as the headline gigawatts.
How this article was built. Public evidence was checked on November 5, 2026; original publication was November 2, 2026. Figures are public facts or NRG calculations from public inputs, with observations, historical benchmarks and forecasts distinguished. This article publishes no NRG estimate. An NRG estimate is a safely generalized range from NRG’s own research, checked against public evidence; no additional range was justified here. NRG’s own research shaped the general framing, while the numerical evidence and calculations are public. Companies are described rather than named. This is business and market research, not a view on any security.
NRG와 함께 일하는 방식
Nathan Research Group과 프로젝트를 시작하세요.
Public forecasts and auction results show interest and procurement volumes. Site decisions also require a clear view of fuel service, permissions, equipment delivery and dependable operation. We connect teams with people who understand those decisions through a compliant research process.
한국 최초의 전문가 네트워크 — 서울, 2013년부터
연결하는 전문가 유형
Data-center power and energy leads
Owner and developer teams who choose between grid, turbines, fuel cells and batteries for new AI data centers.
Utility and interconnection specialists
Large-load connection queues in the US and Korea's grid-impact review for new data-center demand.
Fuel-cell engineers
Stack and system design and reliability.
Manufacturing scale-up specialists
Ramping high-volume production lines.
Gas supply and permitting specialists
Pipeline capacity, air permits and local siting rules for on-site generation.
본 리서치는 공개된 자료와 NRG의 자체 조사를 근거로 작성했습니다. NRG estimate로 표시한 수치는 공개 데이터와 대조해 확인한 반올림 범위입니다. Nathan Research Group은 미공개 중요정보를 요구하거나 중개하지 않으며, 모든 프로젝트를 문서화된 컴플라이언스 절차에 따라 진행합니다.